The days surrounding the finalisation of share allotment in any major public offering tend to generate a distinct kind of anticipation among applicants, and this has certainly held in the case of the Snapdeal IPO, where a large pool of retail and institutional investors placed bids during the subscription window. Once the offer closes, attention naturally shifts toward the outcome of individual applications, and a considerable number of investors have been searching for clarity on how the IPO Allotment Status is determined and what practical steps follow once results are announced. This piece looks beyond the mechanics of checking one’s outcome and instead focuses on what happens structurally in the period between an offer’s closure and the eventual start of trading on the exchanges.
Understanding the Allotment Methodology
India’s securities market regulator has developed a well-defined framework for deciding how the shares in an oversubscribed issue (a fairly common occurrence for issues with strong demand) get distributed amongst the people who applied for them. In general, applications get grouped in broad categories of investors, most commonly qualified institutional buyers, non-institutional buyers and retail individual buyers, and a certain percentage of the total offer is kept aside for each category. Individual categories typically have a systematic methodology applied to them in case of demand outstripping supply for the number of shares being offered under that particular category. For retail investors, this is usually a lottery-based methodology due to the small size of lots (which can’t be split amongst a potentially huge number of retail applicants), whereas for non-institutional and qualified institutional investors, this is more likely to be a proportional allocation based on the size of their application (within the subscription category).
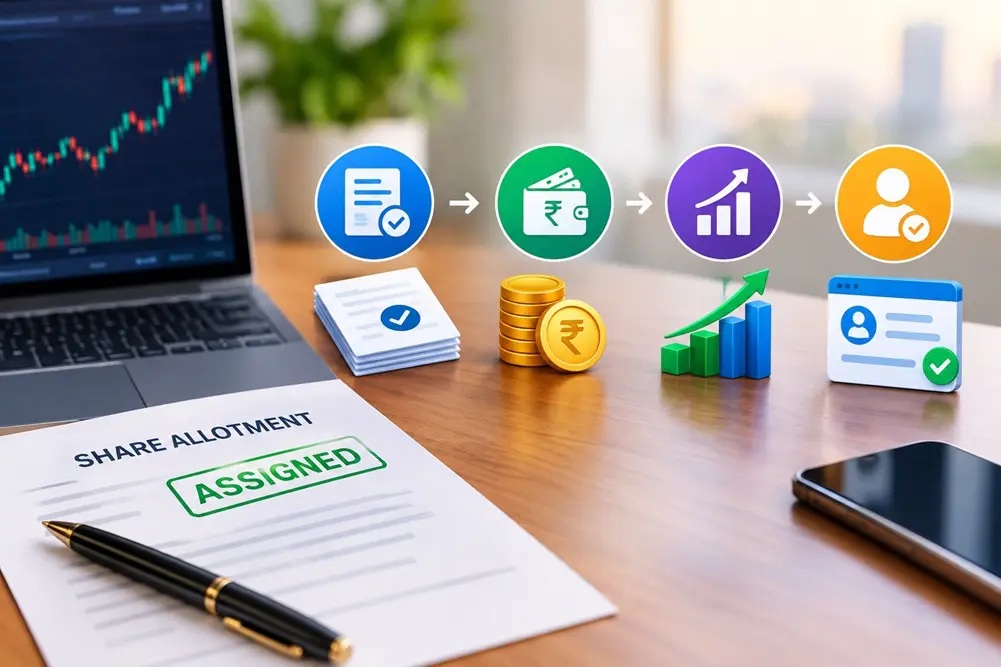
The Journey From Allotment to Listing
Once the registrar finalises allotments, there’s a fairly standard procedure that gets followed speedily (especially with the improvements in India’s capital markets settlement infrastructure in recent years). The shares get credited to the demat accounts of the successful applicants, and the blocked funds in the bank accounts of the unsuccessful applicants (or the unsuccessful portion of the applications for partially allotted applicants) get released back into their accounts. Post this, the stock of the issuing company gets listed (made available for trading) on the stock exchanges, effectively marking the completion of the issue.
Factors That Can Influence Allotment Outcomes
While the process followed while allotting shares to successful applicants is fairly standardised, the outcomes can vary depending on a few factors unique to the subscription pattern of the issue. Categories of investors that see extremely high demand are going to have far lower chances of getting allotted shares even if they apply with a valid PAN and complete application. On the flip side, categories that don’t see near saturation are going to see higher chances across the board, as allotments are made based on demand across applicants within a category (with oversubscription being the driving force behind any particular category’s allotment being lower than another).
Why Application Accuracy Matters
With regard to individual investors, the most important factor in regard to allotment is ensuring that the application has been filled in correctly. PAN mismatches, incorrect demat details or multiple applications with the same PAN can lead to rejections. Investors must ensure that they’ve filled in all the details in the application form accurately on the date of applying for shares. Errors detected on any date succeeding the last date of subscription will not be accepted, and the particular application will fail to be considered.
Preparing for the Post-Allotment Phase
With regard to investors waiting for the allotment outcomes for this issue or any other public issue, understanding this process can help manage expectations during the anxious waiting period between the closure of the subscription window and the announcement of allotment results. Knowing that outcomes are decided based on fairly systematic procedures and are not random can help ease nerves for first-time investors, whereas more seasoned investors can use this information to better time their applications in accordance with the subscription patterns being witnessed. As India’s primary market continues to see robust participation across a diverse range of issues, this knowledge can prove to be invaluable to investors looking to participate in future public issues on the national stock exchanges.